
About UsPricingReviewsContact UsClient Portal loginBook a Free 30-Min Call
About UsPricingReviewsContact UsClient Portal loginBook a Free 30-Min Call
Services
Get caught up
Catch-Up BookkeepingFrom $1,800Books & payroll
BookkeepingFrom $350/monthPayrollGet a quoteSR&ED ClaimsEnd-to-end SR&ED claims, quoted after consultationSR&ED for Software CompaniesQuoted after consultationSR&ED-Ready BookkeepingBooks + T2 for SR&ED claimsTax filing
Corporate Tax (T2)From $800 · nil T2 from $249GST/HST Filing$150 per returnPersonal Tax (T1)From $110 · students from $49Sole Proprietor Tax (T1 + T2125)From $300Start & grow
IncorporationFrom $499 + gov feesVirtual CFOFrom $2,500/monthAI Consulting & AutomationFor small businessesIndustries
Construction & tradesConsultantsTech startupsReal estateHealthcareSee all industries →More
PricingService areasAll services →Accounting and Tax for Ontario Construction Companies and Trades
CPA-led accountants for Ontario construction companies, contractors and trades. Holdbacks, T5018 slips, WSIB, job costing and equipment write-offs handled by a team that knows how a job site actually runs, so you can stay on the tools.
24/7 receptionist, a real person answers.
- Every return is reviewed by a CPA
- No surprise bills
- Reply within one business day
- 24/7 receptionist: a real person answers
- QuickBooks Online, Xero and Dext
- Rated 5.0 stars from 29 Google reviews (read our reviews)
T-Ledgers is a CPA-led accounting firm working with general contractors, renovators, home builders and subtrades across Ontario: framers, electricians, plumbers, roofers, drywallers, concrete and excavation crews, landscapers and finishing trades, from Etobicoke and Mississauga to the rest of the GTA and beyond. Wajahat Ajmal, CPA, FCCA, has been practising since 2020. We do more than bookkeeping. We handle job-by-job bookkeeping, HST, payroll, T5018 slips and corporate and personal tax, and every return is reviewed by a CPA.
Construction books go wrong in ways other industries don’t: holdbacks sitting in limbo, subs paid in cash without slips, a new excavator expensed in full, a job that looked profitable until the change orders were tallied. We set up your file so the year-end numbers already make sense.
Construction tax and bookkeeping issues we handle
Rules, rates and thresholds change. We confirm the current figure for your situation on the call before relying on it.
CCA on equipment, tools and trucks
Equipment generally can’t be written off in one year; it goes into capital cost allowance (CCA) classes. For example, power-operated movable equipment such as excavators and loaders is usually Class 38 (30%), general-purpose vehicles and pickups are usually Class 10 (30%), shop and site equipment that doesn’t fit a more specific class is usually Class 8 (20%), and small tools under $500 can usually go in Class 12 (100%). The half-year rule normally limits the first-year claim, but the reinstated Accelerated Investment Incentive (enacted March 2026) generally gives an enhanced first-year claim for eligible property acquired after 2024 and available for use before 2030. We confirm which rules apply in the year you buy. Budget 2025 has the background. We keep a fixed-asset register so nothing is double-counted or missed, and we record trade-ins and sales properly so recapture or terminal losses don’t catch you off guard.
← Swipe to compare →
| Asset | Usual CCA class | Rate |
|---|---|---|
| Excavators, loaders, skid steers, other power-operated movable equipment | Class 38 | 30% |
| Pickups, vans and general-purpose vehicles | Class 10 | 30% |
| Passenger vehicles above the cost limit | Class 10.1 | 30% |
| Shop and site equipment, scaffolding, trailers for tools (if not in a more specific class) | Class 8 | 20% |
| Small tools costing less than $500 each | Class 12 | 100% |
| Computers and tablets used for estimating and dispatch | Class 50 | 55% |
Law: Income Tax Act s.20(1)(a) (capital cost allowance); Income Tax Regulations s.1100(1) and Schedule II (CCA classes); Income Tax Act s.13(1) (recapture).
Holdbacks under Ontario's Construction Act
Ontario requires a 10% holdback on most contracts, and the prompt payment rules set deadlines for paying proper invoices: 28 days owner-to-contractor, and 7 days contractor-to-sub after being paid (or 35 days after invoicing if the owner doesn’t pay). See the Construction Act. Lien rights have their own short deadlines, and payment disputes can go to construction adjudication under the Act, so it pays to know exactly what’s owed on each job. For tax, a holdback is generally not income until it becomes receivable, and GST/HST on a holdback is generally payable when it’s paid or due, whichever comes first. We track holdbacks receivable and payable as separate balances, job by job, so release dates aren’t missed.
Law: Construction Act (Ontario) s.22(1) (10% holdback); Construction Act (Ontario) s.6.4(1) (owner pays within 28 days); Construction Act (Ontario) s.6.5(1) and 6.5(4) (7 days / 35 days to subcontractors); Construction Act (Ontario) s.31 (expiry of liens); Construction Act (Ontario) s.13.5 (adjudication); Income Tax Act s.12(1)(b) (amounts receivable); Excise Tax Act s.168(7) (tax on retained consideration / holdbacks).
WSIB coverage and clearance certificates
In Ontario, most construction businesses, including independent operators, sole proprietors, partners and executive officers, must have WSIB coverage, with limited exemptions. If you hire subcontractors without a valid clearance certificate, you can be held responsible for their unpaid premiums. We record premiums correctly, reconcile your WSIB reports to payroll and remind you to collect certificates before you pay a sub.
Law: Workplace Safety and Insurance Act, 1997 s.12.2(1) (mandatory construction coverage); Workplace Safety and Insurance Act, 1997 s.141.1 (contractor liability in construction); Workplace Safety and Insurance Act, 1997 s.141.2 (clearance certificates).
T5018 slips for subcontractors
If construction activities are more than 50% of your business income, you report payments to subcontractors for construction services on T5018 slips plus a T5018 Summary. The return is due six months after the end of your reporting period, which can be a calendar or fiscal year, and you only report a sub whose total payments in the period are more than $500, excluding GST/HST. Payments for materials only aren’t reported. Clean vendor records (legal name, address, business number or SIN) make this a quick job instead of a scramble.
Subcontractor or employee?
Calling a worker a sub doesn’t make them one. The CRA looks at control, who supplies tools and equipment, who can hire helpers, who carries the financial risk and who can profit. If the CRA decides a worker is really an employee, you can be assessed for CPP, EI and income tax you didn’t withhold, plus penalties and interest. We help you document the relationship properly and set up payroll when someone is really an employee.
HST, input tax credits and job costing
Ontario HST is 13% (see our GST/HST services). Claiming every eligible input tax credit (ITC) on materials, fuel and rentals, while keeping personal purchases out, is where many trades lose money. Builders who build or substantially renovate a home and then rent it out or move in can trigger the self-supply rule and owe HST on the home’s fair market value, so talk to us before you do. We set up job costing in QuickBooks Online or Xero so you can see which jobs actually make money, including labour, materials, equipment time and change orders.
Law: Excise Tax Act s.165 (GST/HST imposed); Excise Tax Act s.169(1) (input tax credits); Excise Tax Act s.191 (self-supply of residential complexes).
Revenue on long jobs and progress billing
Progress billings are generally income when billed, even if a holdback is withheld. Jobs that run across your year-end need work-in-progress and unbilled amounts tracked so your financial statements, bank covenants and bonding company see a true picture. We set up month-end cut-offs that match how you bill.
Corporate tax, owner pay and instalments
An incorporated contractor’s active business income can qualify for the small business rate on the first $500,000 (shared with associated companies). We plan salary and dividends, keep corporate instalments on schedule and watch for the passive income and associated-company rules that can shrink that limit.
Law: Income Tax Act s.125(1) (small business deduction); Income Tax Act s.125(2) ($500,000 business limit); Income Tax Act s.125(5.1) (business limit reduction); Income Tax Act s.157(1) (corporate instalments).
Tools and travel for tradespeople on payroll
Employed tradespeople may be able to deduct some tool costs and, for temporary work locations at least 150 km from home, eligible travel and lodging through the labour mobility deduction. We give your crew the slips and letters they need.
Law: Income Tax Act s.8(1)(s) (tradesperson’s tools); Income Tax Act s.8(1)(t) and 8(14) (labour mobility deduction).
Bonding, bank financing and bids
Sureties and lenders want reliable financial statements. We produce clean year-end statements and monthly reports, and our Virtual CFO service helps you price bids with real overhead and margin numbers.
Change orders and extras
Change orders are where contractors quietly lose margin: extra work done on a verbal OK, never priced or billed. We set up change orders as their own lines on each job so you can see what was approved, billed and collected. Billed extras are income when billed, and HST is charged on them like any other part of the contract.
Common deductions for contractors
Expenses you incur to earn business income are generally deductible, if they’re reasonable and you keep the receipts. For contractors that usually includes fuel and vehicle costs, small tools, safety gear, WSIB premiums, liability insurance and bonding fees, equipment rental, subcontractors, software, phones and trade training. Personal costs and capital purchases follow different rules.
CRA reviews, audits and record-keeping
The CRA can ask to see your books, receipts, contracts and bank records, and you generally have to keep them for six years from the end of the tax year they relate to. Construction is an industry the CRA watches closely, especially cash payments and subcontractor reporting. We keep your file audit-ready and deal with the CRA for you if a review letter arrives.
Law: Income Tax Act s.230(1) and 230(4) (books and records, six years); Income Tax Act s.231.1(1) (CRA audits); Excise Tax Act s.286(1) and 286(3) (records, six years).
Behind on filings or missed income?
If returns weren’t filed or income wasn’t reported, the CRA’s Voluntary Disclosures Program can offer relief from some penalties and interest when the disclosure is voluntary and complete. We help you decide whether to apply and prepare the returns.
Law: Income Tax Act s.220(3.1) (waiver of penalty or interest); Excise Tax Act s.281.1(1) (waiver of interest).
Who we work with
- General contractors and construction managers
- Residential renovators and custom home builders
- Electrical, plumbing and HVAC subtrades
- Framing, drywall, painting and finishing trades
- Roofing, siding, concrete, masonry and excavation crews
- Landscaping and snow-removal businesses
- One-person operations through to crews of 50 or more
Related industries: Electricians · Plumbers · HVAC companies · Landscaping companies · Trucking companies · Manufacturers · Real estate investors · All industries we serve
Ontario cities we serve: Toronto, Etobicoke, Mississauga, Brampton, Vaughan, Markham, Richmond Hill, Oakville, Burlington, Hamilton, Ottawa, London, Kitchener–Waterloo and Barrie, plus the rest of the GTA and across Ontario. Meet us in person by appointment in Etobicoke or Mississauga, or work with us fully online.
T-Ledgers services for contractors and trades
- Catch-up bookkeeping, from $1,800 per year + HST/GST. Behind by a year or more? We rebuild your books from bank and card statements, sort holdbacks and subs, and file what's overdue in the right order (see catch-up bookkeeping).
- Monthly bookkeeping with job costing. From $500/month + HST/GST (Scale), with books closed by the 10th; quarterly bookkeeping from $350/month + HST/GST (Growth). Your fixed fee is confirmed after a free call (see bookkeeping).
- Bookkeeping Review, $195/month or $295/quarter + HST/GST. Keep your own books and have them reviewed on a set schedule.
- GST/HST returns, $150 per return + HST/GST. HST on progress billings, holdbacks and input tax credits (see GST/HST services).
- Payroll and source deductions. Quoted after a free call (see payroll services).
- T5018 slips and summary. Quoted after a free call.
- Corporate (T2) and personal (T1) tax. Corporate returns quoted after a free call; personal tax returns from $110 + HST/GST, with your final price confirmed after a free call. Owner T1s can be prepared alongside the T2 (see corporate tax and personal tax).
- Virtual CFO, from $2,500/month + HST/GST. Cash-flow forecasting and bid margins for growing contractors (see Virtual CFO).
All prices are + HST/GST. Anything without a listed price is quoted after a free call, and you get the price in writing before any work starts.
How we work with contractors
- Free call. We ask about your jobs, holdbacks, subs, WSIB, equipment and how far behind you are.
- Written price. You get the scope and price in writing before any work starts.
- Setup. We connect your bank feeds, set up job classes and tax codes in QuickBooks Online or Xero, and add Dext for receipts.
- Monthly rhythm. Books closed monthly, HST filed on time, holdback and T5018 records kept current.
- Year-end. Financial statements, T2 and T1, all reviewed by a CPA.
Why contractors and trades choose T-Ledgers
- Built for job sites, not just ledgers. We ask about holdbacks, subs, WSIB and equipment on the first call, so they’re set up correctly from day one rather than fixed at year-end.
- CPA-led, start to finish. T-Ledgers was founded by Wajahat Ajmal, CPA, FCCA. Every return is reviewed by a CPA before it's filed.
- No surprise bills. You get the scope and the price in writing before we start. If the work changes, we agree the new price with you first.
- Price matching, agreed up front. Have a comparable written quote? Bring it to us before you sign your proposal. We can only match a price when it's agreed before the proposal is signed.
- Fast, human answers. We reply within one business day, and our 24/7 receptionist means a real person answers when you call 866-254-5368.
- In person or online. Meet us in person, by appointment only, at our Etobicoke office (102-89 Skyway Ave, Etobicoke, ON M9W 6R4) or our Mississauga office (100 Matheson Blvd E #204, Mississauga, ON L4Z 3P8), or work with us entirely online.
- Your software, set up properly. We work in QuickBooks Online and Xero, and use Dext so receipts go in with a photo.
Meet your CPA
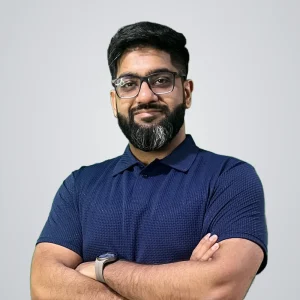
Wajahat Ajmal, CPA, FCCA, Founder, T-Ledgers Accounting. Verify my CPA Ontario membership.
I started my career as an audit associate at KPMG. Since then I’ve worked as an independent contractor for a tax filing company, preparing returns and handling client questions. I hold a BSc in Applied Accounting from Oxford Brookes University and an MSc in Professional Accountancy from University College London. I’m a Chartered Professional Accountant in Ontario and a Fellow of the ACCA. I started taking on my own clients in 2020 and founded T-Ledgers in 2023.
Every return the firm files is reviewed by a CPA. You can read more about the firm on our About page.
What our clients say
 Posted on Google

 Dan
Trustindex verifies that the original source of the review is Google.
I highly recommend T-Ledgers. Their communication is exceptional. You won’t have to wait days for a response. Waji really takes his time to explain things in-depth with his clients. He provides the ins and outs behind every major decision. Our corporation was 2 years behind on filings and Waji and his firm got all the work done in a timely manner, as promised.Posted on Google Umed PulotovWajahat is absolutely amazing. Very knowledgeable, professional, great customer service. I would highly highly recommend T-ledgers accounting for any accounting needs. 100/10!!Posted on Google
 samer chamseddineT-Ledgers has been nothing short of exceptional after my previous accountant had me in hot water. Wajahat explained things in detail throughout the whole process and still continues to keep me updated on my files regularly. Would highly recommend T-Ledgers to anyone who appreciates organization and efficiencyPosted on Google
 Kushtrim CarpentryI highly recommend **T Ledger's Accounting**. He has gone above and beyond for me every single time I’ve needed his help. Even when something is urgent or needs to be handled last minute, he gets it done right away and makes sure everything is taken care of properly. He’s the type of accountant you can genuinely depend on. No matter what situation you’re dealing with, he takes the time to understand it, explains what needs to be done, and handles everything with a high level of professionalism. Reliable, knowledgeable, responsive, and always willing to help. It’s hard to find someone you can trust to handle important financial and accounting matters, and I’ve had nothing but a great experience with T Ledger's Accounting. **Beyond highly recommended. If you’re looking for an accountant you can rely on, this is the place to go.**Posted on Google
 Ali ChaudhryI had a great experience working with Wajahat. He was very flexible, accommodating, and helpful with my schedule. He went out of his way to make the process smooth and stress-free. Highly recommend him to any business ownerPosted on Google
 hurmat shahidThe client portal T-Ledgers uses makes the whole process much easier than dealing with emails and PDFs back and forth. Document sharing is simple, questions get answered quickly, and you can always see where things stand. It's a modern way of handling accounting and I appreciated that.Posted on Google
 Asim AfzalT-Ledgers handled my GST filing and corporate T2 together, which saved me a lot of time coordinating between different people. They understood my business quickly and flagged some bookkeeping gaps I needed to address. Took a lot of stress off my plate and I'll be using them again.Posted on Google
 Atif MahmoodT-Ledgers made filing my corporate taxes straightforward from start to finish. Wajahat was responsive throughout the process and clearly explained what documents I needed to provide and why. The turnaround was reasonable and everything was handled professionally. I'll definitely be coming back next year and would recommend them to any small business owner looking for a reliable accountant.Posted on Google
 Moazzam AfzalI fully recommend Wajahat for one's tax filing needs. He will explain what he's doing and why, rather than just asking for documents and going silent, ensuring the customer is informed at every stage of the process. He is trustworthy and transparent when it comes to pricing and quality of the work for small business tax needs.Verified by TrustindexTrustindex verified badge is the Universal Symbol of Trust. Only the greatest companies can get the verified badge who has a review score above 4.5, based on customer reviews over the past 12 months. Read more
Read more on our client reviews page.
DIY vs a generalist firm vs T-Ledgers
← Swipe to compare →
| DIY | Generalist firm | T-Ledgers BEST VALUE | |
|---|---|---|---|
| Holdbacks, T5018 and WSIB | You research each rule yourself | May treat construction like any other small business | ✓Covered from the first call and built into your books |
| Equipment and truck write-offs (CCA) | Easy to expense in full by mistake | Usually done at year-end only | ✓Fixed-asset register kept current all year |
| Job costing | Spreadsheets, if at all | Often not set up | ✓Job classes in QuickBooks Online or Xero |
| Who checks the return before it's filed | You do | Depends on the firm and who's assigned | ✓Every return is reviewed by a CPA |
| How you're billed | Software fees plus your own time | Often hourly; the final bill can vary | ✓Scope and price in writing up front. No surprise bills |
| Getting an answer | Search online or wait on CRA phone lines | Varies by firm | ✓Reply within one business day; 24/7 receptionist, a real person answers |
| Software | Whatever you set up yourself | May ask you to switch to their system | ✓QuickBooks Online, Xero and Dext |
| Meeting face to face | Not applicable | Varies | ✓In person by appointment in Etobicoke or Mississauga, or fully online |
| Price matching | Not applicable | Rare | ✓Available if agreed before you sign your proposal |
Frequently asked questions: Construction & Trades
If construction activities are more than 50% of your business income, you report payments to subcontractors for construction services on T5018 slips and a T5018 Summary, due six months after your reporting period ends. We can prepare them straight from your books.
Subs you paid more than $500 in the period, excluding GST/HST, for construction services. Payments only for goods, such as materials from a supplier, aren’t reported.
Probably. Ontario requires most independent operators, sole proprietors, partners and executive officers in construction to carry WSIB coverage, with limited exemptions. We’ll look at your situation on the call.
You can be held responsible for the sub’s unpaid WSIB premiums for that work. Get a valid clearance certificate before you pay, and check it again on long jobs.
Generally when it becomes receivable, which is often when the holdback period ends or the work is certified, not when you invoice. GST/HST on the holdback is generally due when it’s paid or becomes due, whichever comes first. We track holdbacks separately so they’re reported in the right year.
Under Ontario’s Construction Act, generally 10% of the value of the work, released once the lien period has passed with no liens preserved.
Under the prompt payment rules, generally within 7 days of being paid by the owner. If the owner doesn’t pay, there’s a notice process and later deadlines. We help you track what’s owed on each job.
Generally yes. Amounts you’ve billed are usually income when billed, even if part is held back. HST is charged on progress billings as you invoice.
A work-in-progress (WIP) schedule lists each open job with its contract value, estimated total cost, costs to date and billings to date, so you can see which jobs are over-billed, under-billed or losing margin. For financial statements under ASPE Section 3400, jobs carried out over time are reported on a percentage-of-completion basis (the completed-contract method is allowed only for a single act or when progress can’t be reasonably estimated), and sureties and lenders expect it. For tax, progress billings are generally income when they become receivable, and the CRA’s archived guidance (IT-92R2) also accepts a completion method for certain fixed-price contracts expected to finish within two years. We set up the method that fits your contracts.
HST on a progress billing is generally payable when the payment is made or becomes due, whichever comes first. It becomes due on the earliest of the invoice date, the date you would have invoiced without undue delay, and the payment date in a written contract. A deposit isn’t taxable until you apply it to the price, for example against your first progress bill. A change order adds to the price of the job, so HST is charged on it when it’s billed or paid. Under a written contract, once the work is substantially complete (the CRA generally treats this as 90% or more), HST on any amount not yet paid or due becomes payable on the last day of the following month. This doesn’t apply to holdbacks, which are taxed when they’re paid or become payable.
Sureties and banks usually ask for year-end financial statements, a WIP schedule for open jobs, aged receivables and payables, and sometimes interim statements during the year. Larger bonding lines or loans may require a review engagement or audit, which only a CPA holding an Ontario public accounting licence can issue. We keep your books, WIP schedule and supporting schedules ready, and work with your surety broker or lender on exactly what they need.
Law: Construction Act (Ontario) s.22(1) (10% holdback); Construction Act (Ontario) s.6.5(1) and 6.5(4) (7 days / 35 days to subcontractors); Income Tax Act s.12(1)(b) (amounts receivable); Excise Tax Act s.168(7) (tax on retained consideration / holdbacks); Excise Tax Act s.168(1), 168(3)(c) and 168(9) (when HST is payable, substantial completion, deposits); Excise Tax Act s.152(1) (when consideration becomes due); CRA GST/HST Memorandum 19-1, Real Property and the GST/HST (construction contracts, holdbacks, deposits); CRA: GST/HST and home construction (progress payments, holdbacks, deposits); CRA IT-92R2 (archived): Income of contractors.
Usually not in full. Equipment and vehicles go into CCA classes and are written off over several years, with special first-year rules. The reinstated Accelerated Investment Incentive (enacted March 2026) generally gives an enhanced first-year claim for eligible property available for use before 2030. We’ll show you what the claim looks like before you buy, so there are no surprises at tax time.
It depends on cash flow, how long you’ll keep it and the tax treatment of each option. Lease payments are generally deductible as you pay them, while purchases go through CCA. We’ll compare both with your numbers.
The sale proceeds reduce the CCA class. If proceeds exceed the class balance, the excess is recapture and is added to income. We record every trade-in so it’s reported correctly.
Tools that cost less than $500 each can usually go into Class 12, which allows a 100% claim. Most small tools aren’t subject to the half-year rule, so the full cost is usually deductible in the year you buy them. More expensive tools go into a regular class.
Often, once profits exceed what you need to live on. An incorporated contractor may get the small business rate on the first $500,000 of active business income, but there are extra costs and filings. We’ll model both on a free call.
Yes, if you’re registered and the materials are for your taxable business. Keep supplier invoices showing their HST number. Personal purchases must stay out.
Usually yes, at 13% in Ontario. Builders who sell or rent out new or substantially renovated homes have special rules, including the self-supply rule, so talk to us before you start the project.
That depends on the actual working relationship, not the label. If you control their hours and tools and they carry no financial risk, they’re likely employees. We’ll review it with you.
Yes. If you’re registered, HST applies to the full price of a taxable construction or renovation job, labour and materials alike, at 13% for work on property in Ontario (jobs on property in another province are taxed at that province’s GST or HST rate). Splitting the invoice into labour and materials doesn’t change the tax. On the other side, you can generally claim input tax credits for the HST you pay on materials, rentals and subcontractors used for the job. If you’re a small supplier ($30,000 or less in taxable sales, including those of associated businesses, over the last four calendar quarters) and not registered, you don’t charge HST.
Federally, yes. The Apprenticeship Job Creation Tax Credit is a non-refundable credit of 10% of eligible wages paid to an apprentice in a Red Seal trade during the first 24 months of their registered apprenticeship, up to $2,000 per apprentice per year. Corporations claim it on Schedule 31 of the T2 return. Ontario’s Apprenticeship Training Tax Credit isn’t available for apprenticeship programs that started on or after November 15, 2017; Ontario now offers grants instead, such as the Achievement Incentive, which pays employers up to $17,000 per apprentice as they reach training and certification milestones.
For an Ontario Canadian-controlled private corporation, active business income up to the $500,000 small business limit is taxed at a combined 11.2% from July 1, 2026: 9% federal plus 2.2% Ontario. Ontario’s rate was 3.2% before that date, so tax years that straddle July 1, 2026 are prorated; a calendar 2026 year works out to about 11.7%. Income above the limit is taxed at the general rate.
Law: Income Tax Act s.125(1) (small business deduction); Excise Tax Act s.169(1) (input tax credits); Excise Tax Act s.191 (self-supply of residential complexes); Income Tax Act s.153(1) (source deductions); Excise Tax Act s.148(1) (small supplier); Excise Tax Act Sch. IX, Part IV (place of supply: real property and related services); CRA: Apprenticeship job creation tax credit; Income Tax Act s.127(9) (eligible apprentice, apprenticeship expenditure); Ontario: financial supports for apprentices and sponsors; Ontario: corporate income tax rates.
Catch-up bookkeeping is from $1,800 per year + HST/GST. GST/HST returns are $150 per return and the Bookkeeping Review is $195/month or $295/quarter (from $450 per review for complex books), also + HST/GST. Payroll, T5018 slips and corporate (T2) returns are quoted after a free call. Personal tax returns from $110 + HST/GST, with your final price confirmed after a free call. You get the price in writing before any work starts.
Yes. Our catch-up service rebuilds your books from bank and card statements, sorts out subs and holdbacks, and files overdue returns in the right order.
Both. We set up job classes, tax codes and bank rules, and use Dext so receipts go in with a photo from the site.
Yes, by appointment at our Etobicoke or Mississauga office, or we can work entirely online.
Get your construction books under control
Book a free call with a CPA-led team that knows holdbacks, T5018 slips and WSIB. We reply within one business day, and you’ll have a written price before any work starts. Call 866-254-5368; a real person answers 24/7.
Reviewed by Wajahat Ajmal, CPA, FCCA. Updated October 15, 2026.
Related services: Bookkeeping · Catch-up bookkeeping · Corporate taxes · Personal tax · Payroll · GST/HST · Virtual CFO · Contact us
Rates and thresholds change, so we link to the official sources for current figures.
Disclaimer: The articles, calculators and other content on this website are general information only, not tax, accounting, legal or financial advice. Calculator results are estimates based on the rates and assumptions shown and may not match your situation. Tax rules change and depend on your province, business structure and the facts of your case, so speak with a CPA, and a lawyer where legal matters are involved, before acting. T-Ledgers accepts no liability for decisions made based on this information. Book a free consult with T-Ledgers.